

Walmart MoneyCard®
3.7

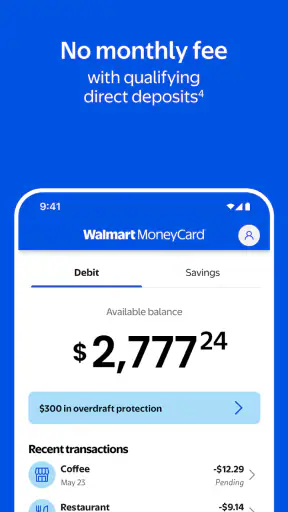
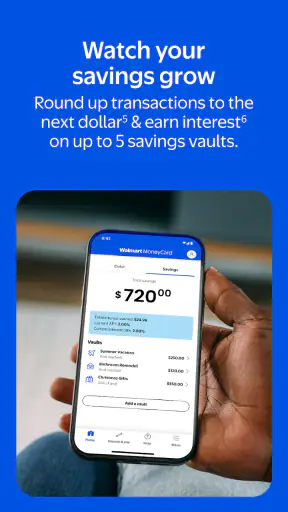
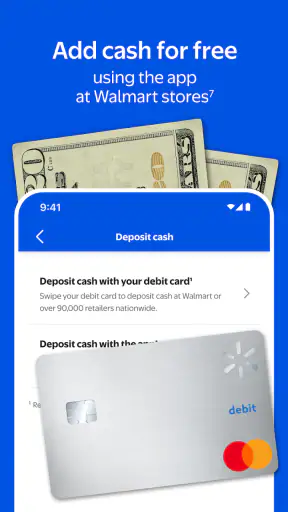
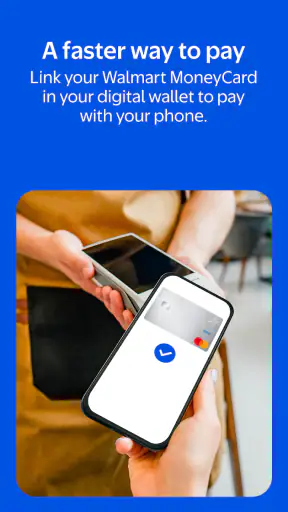
I found Walmart MoneyCard® to be a practical finance app for managing a prepaid money card, but not a complete replacement for every kind of bank account. Its strongest quality is focus: it puts everyday card management in one place without trying to become a full investing, lending, or budgeting platform. That makes it easier to understand for someone who mainly wants to check available money, keep an eye on spending, and handle routine card activity from a phone.
The app is free to install, and it is developed by Green Dot. It belongs to the finance category, carries a Mature 17+ content rating, and has passed the half-million-install mark. Those details give a useful picture of its intended audience: adults looking for a straightforward way to manage their Walmart MoneyCard rather than children or users searching for a broad personal-finance suite.
What using Walmart MoneyCard feels like day to day
My first impression is that the app works best when treated as a control panel for a specific financial product. I would open it before shopping, after a purchase, or when checking whether money is available for an upcoming expense. That narrow purpose is also its main advantage. The experience is less distracting than an app that combines checking, credit cards, loans, investments, rewards, and detailed financial planning on one crowded home screen.
The store summary describes it as a way to bank better with a new app, while the short description identifies the product as Walmart MoneyCard®. In practice, that positioning matters. This is not an app I would choose simply because I wanted a general-purpose banking relationship. I would choose it because I already use, or specifically want to use, the Walmart MoneyCard and need a convenient mobile view of that account.
The basic workflow is easy to understand. I can imagine opening the app to confirm the balance before paying for groceries, reviewing recent activity after a busy shopping trip, or checking the account before deciding whether a bill can be covered. That kind of quick verification is more useful than it sounds. It reduces the need to guess, rely on memory, or wait until a purchase is declined to discover that the available amount is different from what I expected.
There is also a psychological benefit to keeping prepaid spending visible. With a traditional credit card, the balance can feel abstract until the statement arrives. A prepaid card makes the available amount more immediate, and an app built around that card encourages me to check it regularly. I would especially value that habit if I were trying to separate grocery money, household spending, or a fixed weekly allowance from money kept elsewhere.
The strongest part is the simple spending checkpoint
The most convincing reason to use this app is not that it promises to transform personal finance. It is that it can make small decisions clearer. Before leaving a store, I can check whether a payment has appeared. Before making another purchase, I can see whether the remaining balance still matches my plan. That creates a useful loop: spend, review, adjust. For a prepaid product, that loop is more relevant than sophisticated charts or long-term investment tools.
I also think the app suits people who prefer a visible separation between spending money and their main bank account. A dedicated card can make a household budget easier to enforce because the amount available on the card acts as a natural boundary. The app becomes the place to monitor that boundary. It does not replace discipline, but it gives me a quicker way to notice when a plan is drifting.
One practical tip is to check activity at consistent moments instead of opening the app only when something goes wrong. A short review after shopping or at the end of the day can help identify an unfamiliar transaction while the details are still fresh. That is a more useful workflow than treating the app as an emergency tool. It also makes the transaction history more meaningful because I am connecting entries with real purchases rather than scanning a long list weeks later.
Another useful approach is to decide what the card is for before loading or using it. If I use the account only for groceries, travel spending, or a controlled household category, the balance has a clear meaning. If I mix every type of expense into it, the app can still show activity, but I lose the budgeting advantage of the separation. In my view, the product works better when the user gives the card a job.
Where it compares well with ordinary alternatives
Compared with carrying a physical card and checking activity only through occasional notifications or statements, a dedicated mobile app is more convenient. It gives the account a regular place in my routine. Compared with a full bank app, however, Walmart MoneyCard is more specialized. A traditional checking account may be a better fit for someone who wants a broader set of services, more account types, or a single dashboard for several financial products.
Compared with a budgeting app, this app has a different strength. A budgeting app may organize many accounts and categories, but it can require setup, syncing, and interpretation. Walmart MoneyCard is closer to the source of the spending itself. I would use it for immediate card awareness, while using a separate budgeting tool if I needed a complete household plan across multiple accounts.
That distinction helps avoid a common disappointment. Someone downloading it expecting detailed financial coaching may find the experience too narrow. Someone who wants a simple way to stay aware of one prepaid card is more likely to appreciate the limited scope. In this case, fewer ambitions can make the daily task easier.
The meaningful weakness is dependence on a single card ecosystem
The biggest limitation is that the app’s usefulness depends on whether Walmart MoneyCard is the right financial product for me in the first place. If I need a conventional bank account for a wide range of money-management tasks, this app will not solve that broader need. Its focused design is helpful only when the underlying card matches my habits.
I would also be cautious about treating a displayed balance as a complete picture of my finances. The amount associated with one card does not tell me how much I can spend across other accounts, what bills are due elsewhere, or whether a purchase fits my overall monthly plan. The app can support a budget, but it cannot replace one. I would still keep a separate record of recurring obligations and larger goals.
There is a trade-off between simplicity and context. Seeing card activity in a focused interface is convenient, but it may provide less of the wider financial overview available in a full-service banking app. For me, that means the app is strongest as a daily checkpoint and weaker as the only place I manage money.
Another friction point is behavioral rather than technical: the app can make checking easy, but it cannot make every transaction instantly understandable. A recent purchase may need context from a receipt, a shared household explanation, or a little time to recognize. That is why I would not rely on a quick glance alone when reviewing unusual activity. The useful habit is to investigate anything unfamiliar promptly rather than assuming it will sort itself out.
Who should use it, and who should choose something else
I think Walmart MoneyCard is a good fit for adults who already use the card and want a more convenient way to monitor it. It can also suit someone who prefers prepaid spending boundaries, wants to keep a dedicated spending balance separate from a main account, or feels more comfortable with a simple finance interface than with a large banking dashboard.
It may be particularly helpful in an everyday scenario such as managing a fixed grocery budget. I could decide on an amount for the week, use the card for those purchases, and check the app after each trip. If the remaining balance is lower than expected, I have a prompt to review recent activity and adjust the rest of the week. The app does not create the budget, but it makes the budget’s remaining limit easier to see.
I would recommend looking elsewhere if I needed a single application for multiple bank accounts, investments, credit management, or advanced planning. I would also hesitate if I wanted the app itself to teach me how to build a complete financial strategy. A full-service bank app or a dedicated budgeting platform would likely be better for those goals, depending on the person’s priorities.
Users under the Mature 17+ rating should not be the target audience. For an adult, the rating is simply a reminder that this is a financial product intended for mature users, not a casual game or a general shopping companion. I would also make sure that the card’s broader terms and everyday costs fit my situation before making it central to my spending routine; the app’s convenience should not be the only factor in that decision.
Version, adoption, and what that means for a new user
The current version is 2.7.0, and the app requires Android 9 or later. That makes the Android requirement worth checking before installing, especially if I am using an older phone. The product was released on March 12, 2025, so I would approach it as a relatively recent app experience rather than assuming that every older review describes the current interface.
Its average rating is 3.7 from around 3,700 ratings, with roughly 1,900 written reviews. I read that as a mixed but meaningful signal: enough people have used it to form a substantial opinion, yet the score does not suggest universal satisfaction. I would not install it expecting perfection. Instead, I would judge it by the specific task I need it to perform—keeping me informed about my Walmart MoneyCard—and avoid expecting features outside that purpose.
The install count is above 500,000, which shows that the app has reached a sizeable audience without making popularity a substitute for suitability. A person can be perfectly happy with it because it matches a prepaid-card workflow, while another person can reasonably prefer a broader bank application. The important question is not whether it is widely used, but whether its focused approach fits the way I handle money.
On iOS, I would look for the current version and device requirements directly in the relevant store before installing, since the Android version information does not automatically describe another platform. That is a small but worthwhile check for anyone moving between phones. It prevents an avoidable surprise and keeps expectations tied to the platform actually being used.
Small habits that make the app more useful
I would start by turning the app into a deliberate checkpoint rather than a background icon. After using the card, I would review the activity when convenient and compare it with receipts. This is especially valuable when several purchases happen close together, because a quick review can distinguish a normal cluster of spending from something that deserves attention.
I would also avoid using the displayed balance as my only budgeting method. My preferred setup would be a simple note or separate budget for upcoming bills, with the Walmart MoneyCard app used to verify the card-specific amount. That division of labor is important: the app handles immediate account awareness, while the separate plan handles decisions that involve money outside the card.
For shared household spending, I would agree in advance on what the card is meant to cover. That makes the activity history easier to interpret and reduces arguments over whether a purchase belongs in the budget. The app is more useful when its balance and transactions have a clear purpose, not when it becomes a dumping ground for unrelated spending.
Finally, I would keep an alternative payment method available for situations where the card balance is not enough or where I need access to services the app does not provide. That is not a criticism of the mobile experience; it is a sensible consequence of using a specialized prepaid product. A focused tool works best when I understand its boundaries.
My final recommendation
After looking at how it fits into real routines, I see Walmart MoneyCard as a focused companion for Walmart MoneyCard users rather than a universal banking solution. Its value comes from making one spending account easier to check and understand. The interface concept is strongest when I want quick awareness, a visible spending limit, and a simple way to review card activity from my phone.
I would recommend it to an adult who wants that focused control and is comfortable keeping broader financial planning somewhere else. I would skip it as my primary finance app if I needed a complete view of several accounts, deeper budgeting tools, or a full-service banking relationship. The key trade-off is simple: focused card management in exchange for a narrower financial picture.
For the right user, that is a fair trade. I would install it, define what the card is for, and build a habit of checking activity after meaningful spending. Used that way, the app can make everyday money decisions less uncertain without pretending to solve every financial problem. That honest, limited role is exactly why I think it is worth considering.
3.7
1.88K Reviews
Pros
- No monthly fee when you receive $500+ in direct deposits.
- Mobile check deposit lets you add eligible checks from your phone.
- Early direct deposit may provide access to paychecks sooner.
- Cash reloads are available at participating Walmart locations.
- Visa Zero Liability can help protect against unauthorized purchases.
Cons
- A monthly fee may apply if you do not meet the direct-deposit waiver.
- ATM withdrawals outside the MoneyPass network can incur extra fees.
- Some features and fees vary by cardholder eligibility and location.
- Cash reload availability depends on participating retailers and their limits.
- It is not a traditional bank account and may lack full banking services.


